

It’s official.
Anthropic, the brains behind the Claude AI model, is going public. The S-1 forms are filed, the IPO is expected next month… and it even has a ticker symbol: “ANT.”
We’ve seen this coming for months. But it’s still a very big deal.
The IPO is expected to value the company at up to $2 trillion, likely surpassing SpaceX’s (SPCX) massive IPO earlier this year and easily making it one of the top 10 largest companies in the world by market cap.
So… should you buy shares of ANT once they start trading?
Maybe.
I’ll be up front… My system can’t be much help here.
My Green Zone Power Ratings system rates stocks with established trading histories based on their momentum, size, volatility, value, quality and growth. We won’t have meaningful data on any of those factors (with the sole exception of size) when the shares start trading.
A year or two from now, my system will do a fantastic job of rating Anthropic. On day one, it won’t tell us much.
That doesn’t mean we can ignore it. AI is a circular, interconnected world, and Anthropic’s success or failure will hit the “Magnificent Seven” hard… and the S&P 500 Index along with them. Just look at the compute commitments in Anthropic’s filings. The company has $120 billion in compute commitments with SpaceX, $114.5 billion with Google Cloud, $110 billion with Amazon (AMZN) and $44.9 billion with Microsoft (MSFT).
Anthropic could be responsible for as much as 28% of SpaceX’s revenues for the first quarter of next year. If Anthropic flops, SpaceX goes down with it.
A lot is riding on this IPO being a rip-roaring success.
On most Tuesdays, I like to do a “sector X-ray,” where I take a deep dive into one of the S&P 500’s major industrial sectors.
With the Anthropic IPO dominating the headlines, I’m doing something a little different. I’m X-raying the AI giants with the most at stake: the Mag 7 and SpaceX.
So, let’s jump in!
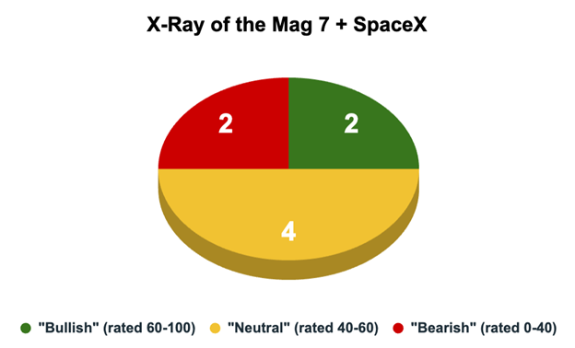

There are only eight stocks to consider here… and six of them don’t look great.
Two of the stocks rate as “Bullish,” meaning a score of 60 or higher out of 100. (For those new to my system, “Bullish” rated stocks outperform the S&P 500 by double on average over the following year.)
Half are rated “Neutral,” meaning my system would expect them to more or less move in line with the broader market. Given the sheer size of these companies, that’s not hard to understand.
When you “are” the market, it’s hard to meaningfully outperform.
The last two stocks rate as “Bearish.”
Keep in mind that every stock on this list takes a hit for its size. My Green Zone Power Ratings favor smaller companies, all else equal. But as the past several years have proven, big stocks can keep getting bigger.
So, let’s dig deeper to see where these stocks tend to score well.
Where Do the Mag 7 and SpaceX Pick Up Points?
The Green Zone Power Rating system is a composite score based on six primary factors: momentum, size, volatility, value, quality and growth, each of which comprises several sub-factors.
Given that these are literally the largest companies in human history by market cap, it makes sense to skip the size factor for now.
Let’s see where these stocks tend to rate the best.

No one is ever going to argue the Mag 7 and SpaceX are cheap…
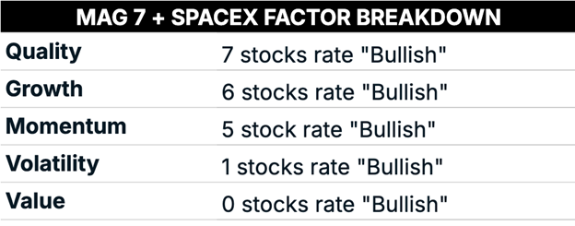
Not a single one of the eight rates as “Bullish” on value. And only one rates as “Bullish” on value.
But these are solid growth stocks that make ungodly amounts of money. Seven out of the eight rate as “Bullish” on quality and six rate as “Bullish” on growth.
They are expensive… they may be a little volatile… But they’re also fantastic businesses that, despite their gargantuan size, just keep growing.
The Mag 7 and SpaceX by the Numbers
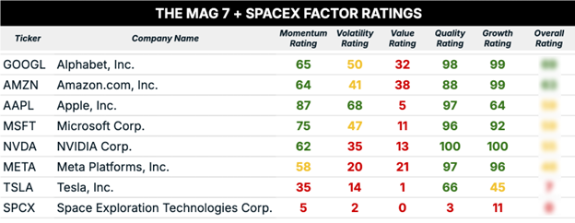
Let’s break it down even further. I included the factor ratings of all eight stocks below:

I’ll start with addressing the elephant in the room…
SpaceX rates terribly on my system. Its overall Green Zone rating rounds down to a literal zero.
To be fair, my system isn’t designed to analyze recent IPOs like SpaceX, so I would take the numbers with a healthy grain of salt. But as I mentioned earlier, SpaceX has major concentration risk in Anthropic.
SpaceX isn’t really a play on space exploration. It’s an AI compute provider that happens to own a rocket and satellite business on the side.
There’s nothing wrong with that. It’s been a booming business for the company. But you need to know that before you buy the shares.
Of the remaining stocks on the list, the two “Bullish” rated are Alphabet (GOOGL) and Amazon.
Like SpaceX, Alphabet and Amazon are hyperscalers. They’ve built out enormous computing infrastructure that they rent out to their clients. But unlike SpaceX, Alphabet and Amazon have more diversified revenue streams.
Alphabet runs the world’s largest search engine, Google, owns the largest mobile operating system, Android and offers comprehensive business cloud services beyond basic compute rental.
And Amazon is the world’s largest retailer with a growing global logistics business and the world’s largest cloud computing provider.
I still believe the AI revolution is in the early innings. But if there are any major hiccups in the months ahead, Alphabet and Amazon should be in a stronger position to ride them out.
To good profits,
Adam O’Dell
Editor, What My System Says Today

P.S. My colleague and Chief Strategist of Strategic Fortunes Ian King believes that Anthropic — along with SpaceX and OpenAI — could help create some of the most valuable businesses in history.
Part of the evidence, he says, is hiding inside a strange box he reveals in a recent video.
But even if Anthropic proves to be a worthwhile investment, Ian believes the bigger opportunities may lie elsewhere: “The bigger opportunities are often not to invest in the big companies… But to invest in the network they’re all building on.”
Check out Ian’s full video to see what he’s uncovered — and where he’s looking for the biggest opportunities.