

Every earnings season, investors make the same bet.
A company beats on earnings. It beats on sales. The headline says “blowout quarter.”
So, the stock should go up, right?
Not this time.
I ran a screen this week for every stock in the S&P 1500 that beat Wall Street’s earnings estimate by more than 10% last quarter and beat its sales estimate by more than 10%.
I also asked for a strong score on Adam’s Green Zone Power Ratings. That’s a high bar. Only 33 stocks cleared it.
Then I checked what those 33 stocks did over the past month.
Seventeen went up. Sixteen went down.
That’s a coin flip.
And it tells you something most investors never learn: a beat is a report card on the past.
The market pays for what comes next.
Same Oil… Opposite Results
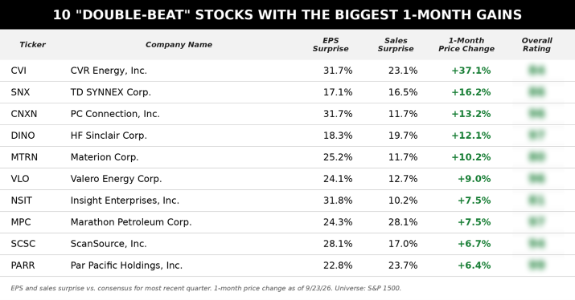

Look at who made the top 10. CVR Energy Inc. (CVI) jumped 37.1% in a month. HF Sinclair Corp. (DINO), Valero Energy Inc. (VLO), Marathon Petroleum (MPC) and Par Pacific Holdings Inc. (PARR) round out five refiners.
Now look at who didn’t make it.
Seven refiners passed my screen.
All seven are up over the past month, by an average of 11.6%.
Seven oil drillers and service companies passed the same screen.
Devon Energy (DVN), Occidental Petroleum (OXY), Permian Resources (PR), SM Energy (SM), Crescent (CRGY), Talos (TALO) and Cactus (WHD).
All seven are down, by an average of 5.3%.
Here’s the kicker.
The drillers beat by more. Their average earnings surprise was 33.6%.
The refiners came in at 28.1%.
Same industry. Same oil. Bigger beats. Worse stocks.
The Market Bought the Spread, Not the Barrel
A driller gets paid for pulling crude out of the ground. A refiner gets paid for the gap between what it pays for crude and what it gets for diesel and gasoline. Traders call that gap the “crack spread.”
And right now, that gap is the story of the year.
The U.S. diesel crack spread hit $102.20 a barrel earlier this month. That’s a record, above even the 2022 energy crisis. National diesel prices topped $6 a gallon for the first time ever.
Why? Ukraine has spent months hitting Russian refineries. Russian throughput has fallen close to a 20-year low.
In July, global refineries ran nearly 5 million barrels a day below year-ago levels.
You can see it in the results. Marathon’s refining margin hit $36.33 a barrel last quarter. A year ago, it was $17.58.
So the refiners didn’t just beat. They beat because of something still happening today. The drillers beat on a price they don’t control, and the market isn’t willing to pay for it twice.
That same idea runs through the other big group on the list: TD SYNNEX Corp. (SNX), PC Connection (CNXN), Insight Enterprises (NSIT) and ScanSource (SCSC). These are the middlemen who sell and install the servers, PCs and networking gear that companies are buying right now. TD SYNNEX posted record results last quarter. Investors bet the orders would keep coming.
On Thursday, TD SYNNEX showed they are. It beat again. Sales jumped 37.7% from a year ago to $21.6 billion, about 13% above what analysts expected. Adjusted earnings rose 58.7% to $5.68 a share.
Then it guided next quarter’s sales to $22.2 billion and earnings to $5.90 a share at the midpoint – surpassing Wall Street estimates of $19.6 billion and $4.87, respectively.
What To Do With the Double-Beat List
If you own a refiner, enjoy the ride. But know what’s holding it up. Earlier this month, President Donald Trump said Russia and Ukraine agreed to stop hitting each other’s energy sites. President of Ukraine Volodymyr Zelenskyy said no deal exists.
That’s one headline away from a very different chart. Goldman Sachs expects diesel margins to hold near $63 a barrel into 2027. That’s triple a normal margin, but it’s well below today. Keep your stop in place.
If you own a driller that beats and falls, don’t average down on the beat. The market already told you it doesn’t care about last quarter.
And for every stock you own, ask the question this list asks: Is the reason it beat still true today?
That question matters even more next week. Three companies report, and in every case, what they say about the future will count more than the number itself.
“Bullish” Earnings to Watch
These stocks are expected to beat their earnings per share (EPS) from the previous quarter. And if those expectations are met or exceeded, they could potentially trade higher.
For this screen, stocks must meet four criteria:
- 10 or more analysts cover the stock.
- The average analyst recommendation is a “Buy.”
- It BEAT analysts’ EPS estimates for the previous quarter.
- The average analyst estimate for the current quarter’s EPS is greater than the previous one.
Here is the one company that made this week’s list:
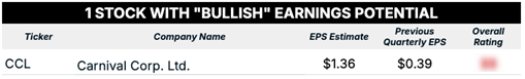

Carnival Corp. (CCL) reports earnings on Tuesday, September 29, before the bell. The estimate is $1.36 a share, up from $0.39 last quarter.
Don’t read too much into that jump. Carnival’s third quarter covers the summer, the busiest cruise season of the year. That’s always when it makes the most money.
The better number is this one. A year ago, Carnival earned an adjusted $1.43 in this same quarter. Analysts now expect less.
That’s a low bar for a company on a roll. Carnival just posted its 12th straight quarter of record net yields, the key measure of what it earns per passenger.
Adjusted earnings jumped 15% last quarter. Customer deposits hit a record $9 billion. And back in June, management said the company was 93% booked for the year.
That’s money already in the bank.
So why the low bar?
Fuel.
Crude climbed above $100 a barrel this month. Goldman Sachs, Barclays, Stifel and Deutsche Bank all cut their price targets in mid-September.
That’s exactly the setup Adam’s system looks for. The analysts cut. The bookings didn’t.
One honest note.
Look at the overall rating.
Carnival sits in Bearish territory on Adam’s Green Zone Power Ratings. The quarter looks good. The stock still has problems, including a big debt load.
This is a trade on one report, not a long-term buy.
“Bearish” Earnings to Watch
For our “bearish” earnings screen, we’re only looking for two things:
- 10 or more analysts must cover the stock.
- The average analyst estimate for the current quarter’s EPS is less than the previous quarter’s.
We want companies that are covered by a sufficiently large group of Wall Street analysts who collectively expect the company to report a quarter-over-quarter (QOQ) decline in earnings.
Here are two companies that passed this screen:
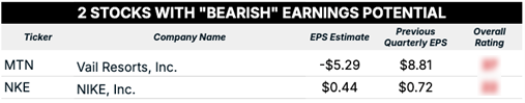

Vail Resorts Inc. (MTN) reports earnings on Monday, September 28, after the close. The estimate is a loss of $5.29 per share, compared with a profit of $8.81 per share last quarter.
Ignore that swing. Vail’s fourth quarter is summer. Ski resorts lose money in summer.
That’s normal.
What isn’t normal is last winter.
Skier visits fell 15.5% in the third quarter. Resort revenue fell 7%. Net income dropped 19.3%. Vail cut its full-year profit guidance.
And the next winter doesn’t look better yet.
Early sales of Epic Passes for the 2026 to 2027 season ran about 10% behind last year by late May.
That’s the number to watch Monday. Vail updates its pass sales with this report. Those passes are next year’s revenue, sold in advance. If units are still down 10%, the problem isn’t one bad snow year.
There’s one more red flag.
Vail pays a $2.22 quarterly dividend. That payout now exceeds the company’s own earnings forecast. Debt rose 11.5% to $3.02 billion.
At some point, something gives.
Nike Inc. (NKE) reports earnings on Thursday, October 1, after the close. The estimate is $0.44 a share, down from $0.72 last quarter.
The stock is down nearly 40% this year. And the bar still looks too high.
UBS expects Nike to miss by about a nickel. Both UBS and BMO think Nike will reset its full-year outlook.
Stifel cut its target to $40 this week and trimmed its earnings estimates for the next two years. Greater China sales fell 17% last quarter, and management expects more decline.
There are bright spots.
Running has grown by double digits for five straight quarters. The World Cup could add about $300 million in sales this quarter.
But look at the price. Nike trades at about 21 times forward earnings. Adidas trades at about 11.
What To Do Before Monday
Here’s your plan for next week.
If you own Vail, act before Monday’s close, not after. Set your stop now.
Then read the release for one line: season pass units. That tells you whether next winter is fixed.
If you own Nike, don’t wait for Thursday night. A turnaround stock trading at twice its rival’s price has no room for a guidance cut. Nike’s Investor Day is November 16 to November 17. Any real fix gets unveiled there, not next week.
If you’re looking at Carnival, watch the booking outlook for 2027, not just the quarter. Carnival said in June that 2027 bookings were ahead of last year on both volume and price. If that holds, the fuel scare was the opportunity.
And carry the lesson from the double-beat list into every report you read this season.
The beat is last quarter. The stock is next quarter.
Have a great weekend, all.
Until next time…
Safe trading,
Matt Clark, CMSA®
Chief Research Analyst, What My System Says Today
