

Eight straight losing days.
That’s how long chip stocks fell heading into October 16.
The Philadelphia Semiconductor Index hadn’t strung together a losing streak like that since 2008. On that Friday alone, tech stocks lost more than $1 trillion in value.
You’d think tech companies were blowing their numbers.
They’re not. They’re crushing them.
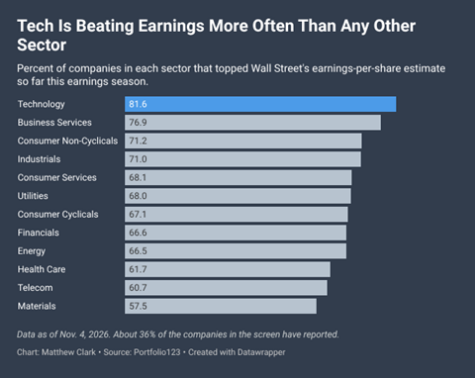

Look at the top bar.
Of the tech companies that have reported, 82% have beaten their earnings estimates. No other sector tops 77%.
And these aren’t squeakers, either. The median tech company beat by 9.6%, the widest margin of any sector.
Sales tell the same story. Nearly 84% of tech companies beat their revenue estimate, also tops on the board.
But here’s the number I like most…
Analysts raised their tech estimates 1,088 times. They cut them 419 times. That’s 2.6 raises for every cut. No sector has a better ratio.
Now look at the bottom of the chart. Materials beat just 57.5% of the time. Analysts cut those estimates 780 times and raised them only 534 times.
So why is tech the sector getting sold?
It’s not the earnings. It’s fear.
In mid-October, oil topped $100 a barrel. The 10-year Treasury yield hit 5.10%. And investors started asking who pays for all those AI data centers. Nvidia Corp. (NVDA), the biggest profit machine in the sector, fell 13.6% over the past four weeks.
Here’s the thing about fear. It sells everything at once. It doesn’t check the books.
Earnings do.
And next week, Adam’s Green Zone Power Ratings system flagged two AI stocks on opposite sides of that line.
One has the numbers on its side. The other has earned the fear.
“Bullish” Earnings to Watch
These stocks are expected to beat their earnings per share (EPS) from the previous quarter. And if those expectations are met or exceeded, they could potentially trade higher.
For this screen, stocks must meet four criteria:
- 10 or more analysts cover the stock.
- The average analyst recommendation is a “Buy.”
- It BEAT analysts’ EPS estimates for the previous quarter.
- The average analyst estimate for the current quarter’s EPS is greater than the previous one.
Here are the 10 companies that made this week’s list:
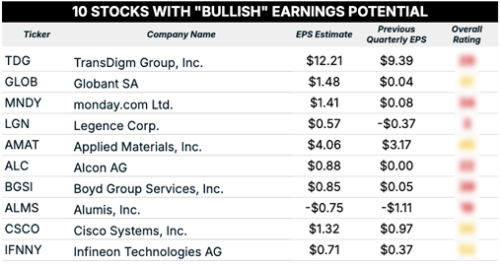

Applied Materials Inc. (AMAT) reports Thursday, November 12, after the close. The estimate is $4.06 a share, up from $3.17 last quarter.
That $3.17 is the company’s GAAP number. On an adjusted basis, Applied earned a record $3.50 last quarter. So the jump Wall Street expects is closer to 16% than 28%.
That’s a bar Applied can clear.
Start with the company’s own guidance. Management called for $4.02 per share, give or take $0.20. That puts the top of the range at $4.22, and the consensus estimate sits just above the midpoint. Now look at how Applied has handled its guidance this year. It has landed above the midpoint in every quarter of fiscal 2026. Last quarter, it guided to $8.95 billion in sales and delivered a record $9.12 billion.
And the business is speeding up.
Sales went from a 2% decline in the first quarter to 11% growth in the second and 25% growth in the third. This quarter, management is guiding for $10.25 billion. That would be about 51% growth from a year ago, when sales slipped 3% to $6.80 billion.
Here’s why that matters right now…
Applied doesn’t need to pick a winner in the AI race. It sells the tools every chipmaker needs to build the chips. And CEO Gary Dickerson said AI adoption is driving record demand for those tools.
Meanwhile, the stock trades around $369. That’s about half its 52-week high of $739.67. It sells for under 20 times next year’s expected earnings.
Now the caveat. Equipment sales are lumpy. One delayed shipment or a new export rule on China can knock a quarter off course. Applied’s next quarter also runs 14 weeks instead of the usual 13, which adds costs. So here’s my read. The sell-off priced Applied like a troubled company. The numbers say it’s a company setting records.
“Bearish” Earnings to Watch
For our “bearish” earnings screen, we’re only looking for two things:
- 10 or more analysts must cover the stock.
- The average analyst estimate for the current quarter’s EPS is less than the previous quarter’s.
We want companies that are covered by a sufficiently large group of Wall Street analysts who collectively expect the company to report a quarter-over-quarter (QOQ) decline in earnings.
Here are 10 companies that passed this screen:
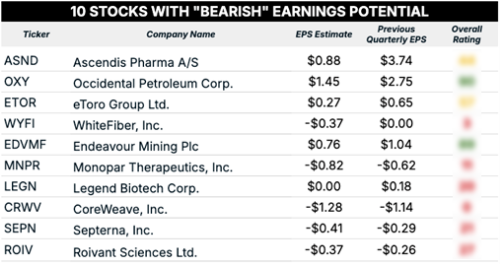
CoreWeave Inc. (CRWV) reports Tuesday, November 10, after the close. The estimate is a loss of $1.28 a share. Last quarter, it lost $1.14.
CoreWeave rents out Nvidia chips to AI companies. And business is booming. Sales more than doubled last quarter to $2.58 billion. Its backlog sits at about $104 billion.
So what’s the problem?
CoreWeave borrows to buy those chips. A lot.
It carries about $50 billion in debt. Last quarter, its interest bill hit $640 million. A year earlier, it was $267 million.
And management already told you it’s getting worse. For this quarter, CoreWeave guided interest expense to $860 million to $940 million.
Here’s the math nobody’s talking about…
At the midpoint, interest jumps about $260 million from last quarter. Adjusted operating income, the profit before that interest, rises only about $100 million at the midpoint of guidance. That leaves the loss roughly $160 million deeper.
Spread that over about 550 million shares, and you get roughly $0.29 a share. Add it to last quarter’s $1.14 loss, and you land near $1.43. That’s worse than the $1.28 Wall Street expects.
My math is rough. Taxes, stock pay and a rising share count can move it around. But the direction is hard to argue with.
And the market has started to notice. In the week before October 16, CoreWeave’s stock fell about 25%. Its 2030 bonds sold off hard, pushing their yield to nearly 16%.
That’s what lenders charge a company they worry about.
The stock now trades around $48.
To be fair, CoreWeave has real support. Nvidia agreed to buy its unused capacity through April 2032. And the company added more than $25 billion in new customer commitments early in the third quarter.
But a big backlog doesn’t pay this quarter’s interest. Cash does. And CoreWeave guided to $11.5 billion to $13.5 billion in spending this quarter alone.
What To Do Next Week
Here’s your plan.
If you’re watching Applied Materials, Thursday night is your moment. Check the sales number first.
If it lands near $10.25 billion or higher, the 2027 outlook becomes the story. Listen for how management talks about next year’s demand. That’s the setup the system wants.
If you own CoreWeave, don’t add ahead of Tuesday. Skip the backlog headline and go straight to interest expense and the 2027 spending plan.
If interest lands at the high end of guidance, a stock already down sharply could have further to fall.
And keep both tables handy. The rest of the names report throughout the week.
Fear sold every AI stock at once. Next week, earnings will start sorting them.
Until next time…
Safe trading,
Matt Clark, CMSA®
Chief Research Analyst, What My System Says Today
