

This is something you don’t see very often.
Analysts spent the summer raising their earnings estimates.
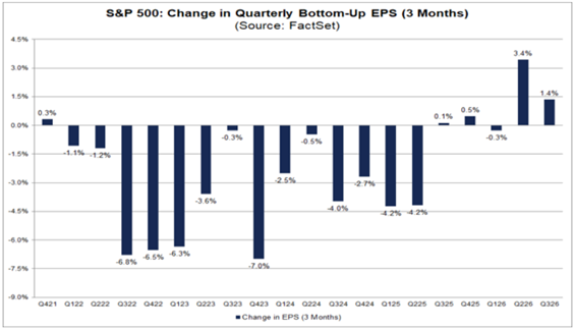

Look at the left side of that chart first.
From the start of 2022 through the middle of 2025, the bars point down. Fourteen quarters in a row.
Analysts started each quarter hopeful, then cut.
In some quarters, they cut by 6% or 7%.
That’s normal.
Over the past 20 years, the S&P 500 Index estimate has fallen by 4.2% during a typical quarter. Over the past five years, it has fallen by 2.2%.
Now look at the right side. Four of the last five bars point up.
For the third quarter, analysts raised their estimate 1.4%, from $88.64 a share to $89.84. They now expect earnings to grow 29.5% from a year ago. On June 30, they expected 26.7%.
Companies are pushing the number higher, too.
FactSet counts a record 72 S&P 500 companies that raised their own third-quarter outlook. Why should you care?
Last week, I showed you the Lowball List. Those companies beat because Wall Street set the bar low.
This season, the bar went up. That means a beat tells you more than usual. And a miss stings more than usual.
Next week, the banks go first.
Look at the two tables below.
Of the 18 names on next week’s lists from Adam’s Green Zone Power Ratings system, 16 are financial stocks. All 10 on the bearish list are banks, brokers or insurers. Six of the eight are on the bullish list.
Same industry. Same week. Opposite calls.
So, the system isn’t saying banks are good or bad. It’s saying something about which kind of bank earnings hold up.
I’ll show you one from each side.
“Bullish” Earnings to Watch
These stocks are expected to beat their earnings per share (EPS) from the previous quarter. And if those expectations are met or exceeded, they could potentially trade higher.
For this screen, stocks must meet four criteria:
- 10 or more analysts cover the stock.
- The average analyst recommendation is a “Buy.”
- It BEAT analysts’ EPS estimates for the previous quarter.
- The average analyst estimate for the current quarter’s EPS is greater than the previous one.
Here are the eight companies that made this week’s list:
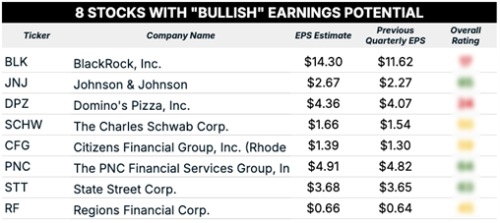

The Charles Schwab Corp. (SCHW) reports Thursday, October 15, before the open. The estimate is $1.66 a share, up from $1.54 last quarter.
A year ago, Schwab earned $1.31 in this same quarter. So, Wall Street expects 27% growth.
Here’s why I like the setup.
Schwab makes most of its money from balances. Client assets. Client cash. Client loans. Those balances don’t reset every quarter. They carry over, and lately they keep growing.
Start with the money coming in the door.
Schwab pulled in $64.8 billion in core net new assets in August. That’s a record for the month and up 46% from a year ago. Total client assets hit $13.41 trillion, up 19%.
Then look at borrowing. Margin loans reached $177.6 billion in August. That’s up 92% from a year ago. Schwab earns interest on every one of those dollars.
You can see it in the margin. Schwab’s net interest margin hit 3% last quarter, up 0.12 percentage points from the quarter before.
One caveat. Trading cooled off in August. Clients made 9.8 million trades a day, down 16% from July. That’s still up 37% from a year ago, but it’s the number to watch.
And not everyone’s on board.
Bank of America keeps an Underperform rating on the stock with a $95 price target. Shares closed near $97 on October 6, about 15% below their 52-week high.
“Bearish” Earnings to Watch
For our “bearish” earnings screen, we’re only looking for two things:
- 10 or more analysts must cover the stock.
- The average analyst estimate for the current quarter’s EPS is less than the previous quarter’s.
We want companies that are covered by a sufficiently large group of Wall Street analysts who collectively expect the company to report a quarter-over-quarter (QOQ) decline in earnings.
Here are 10 companies that passed this screen:
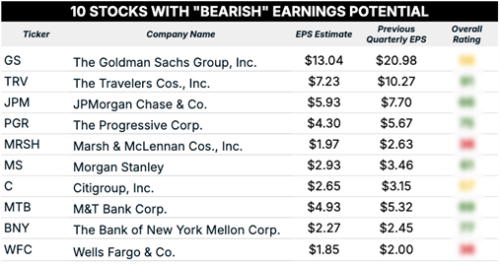

The Goldman Sachs Group (GS) reports on Tuesday, October 13, before the open. The estimate is $13.04 a share, down 38% from $20.98 last quarter.
Wait. Isn’t Goldman booming?
It is. That’s the problem.
Last quarter was everything going right at once.
Net revenue jumped 39% to $20.34 billion. Equities trading hit $7.42 billion, its third straight record. Investment banking fees jumped 55%. And gains on its private equity investments more than tripled from a year ago.
Wall Street doesn’t expect a repeat. The $13.04 estimate sits below the $17.55 Goldman earned in the first quarter, too.
Here’s the number that jumps out at me.
A year ago, Goldman earned $12.25 in the third quarter. So, the estimate calls for about 6% growth. That’s in a season when Wall Street expects the S&P 500 to grow earnings by almost 30%.
Now compare it with Schwab. Schwab’s earnings come from balances that carry into the next quarter. Goldman’s comes from deals and trades. It has to win most of them again every 90 days.
To be fair, Goldman has things going for it.
Management said in July that it expects “materially higher incentive fees” in the third and fourth quarters. Its investment banking backlog sits at a five-year high.
But the headline next Tuesday will compare this quarter with $20.98. A 38% drop is hard to sell, even with a beat.
Some analysts already see it.
In September, Citigroup cut its price target to $1,050 from $1,200. UBS cut its target to $1,010 from $1,150. The stock closed near $894 on October 6, about 23% below its 52-week high.
So, some of this is already in the price. I wouldn’t count on all of it.
What To Do Next Week
Here’s your plan.
If you’re looking at Schwab, Thursday morning is your moment.
Watch two numbers: net interest margin and margin loan balances.
If the margin holds at 3% or better and loan volume continues to climb, the estimate looks too low. That’s the setup the system wants.
If you own Goldman, don’t add ahead of Tuesday. Read past the headline.
A beat on a bar that dropped 38% isn’t the same thing as growth. Listen to what management says about that backlog and those incentive fees. If they can’t point to a strong fourth quarter, I’d expect the stock to have a tough time getting back to its highs.
And keep both tables handy.
Goldman, JPMorgan Chase & Co. (JPM) and Johnson & Johnson (JNJ) all report Tuesday morning. BlackRock follows on Wednesday. Schwab closes out the big week on Thursday.
When Wall Street raises the bar, the steady earners clear it. The flashy ones have to jump.
That’s all from me… have a great weekend.
Until next time…
Safe trading,
Matt Clark, CMSA®
Chief Research Analyst, What My System Says Today
