Energy is throwing the biggest earnings party on Wall Street right now.
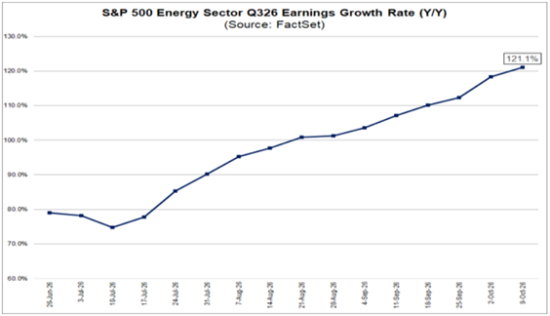
According to FactSet, the energy sector is on track to report 121.1% year-over-year (YOY) earnings growth for the third quarter.
That’s the highest of all 11 sectors.
And it isn’t even close.
Back on June 30, analysts were anticipating 79.3% growth. Since then, they’ve been scrambling to catch up.
Estimated earnings for the sector climbed 23.3% over the course of the quarter — from $47 billion to $58 billion.
No other sector saw a bigger upward revision.
Look at the shape of that line.
Analysts started the summer near 79%, dipped below 75% in early July… then marched higher almost every single week through October 9.
What’s driving it? Oil.
West Texas Intermediate crude averaged $85.68 a barrel in the third quarter. A year earlier, it averaged $64.97. That’s a 32% jump — and it flows straight to the bottom line for drillers, refiners and pipeline operators.
But here’s what most folks will miss…
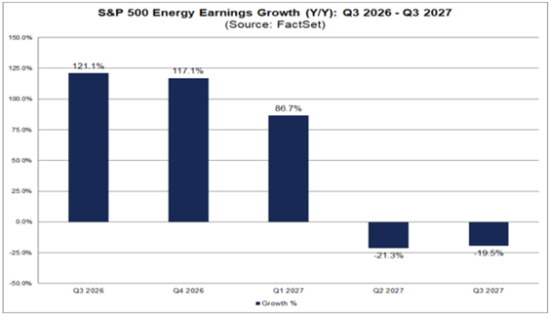
Analysts expect the party to keep rolling for a while. They’re projecting 117.1% growth in the fourth quarter and 86.7% in first-quarter 2027.
Then the music stops.
For the second and third quarters of 2027, Wall Street sees energy earnings falling 21.3% and 19.5%, respectively.
Why the cliff?
Simple math. Once energy companies lap a full year of $85 oil, the easy YOY comparisons disappear.
Growth that looked spectacular turns into a tough hurdle.
So what does that mean for you?
It means the window for energy earnings surprises is open right now — not next summer. The next two or three reporting cycles are where the money gets made.
After that, you need to be a lot pickier.
And that’s exactly where the Green Zone Power Ratings system earns its keep.
It doesn’t care about headlines. It looks at the data — and right now, it’s pointing to one energy name in particular heading into next week.
“Bullish” Earnings to Watch
These stocks are expected to beat their earnings per share (EPS) from the previous quarter. And if those expectations are met or exceeded, they could potentially trade higher.
For this screen, stocks must meet four criteria:
- 10 or more analysts cover the stock.
- The average analyst recommendation is a “Buy.”
- It BEAT analysts’ EPS estimates for the previous quarter.
- The average analyst estimate for the current quarter’s EPS is greater than the previous one.
Here are the 10 companies that made this week’s list:
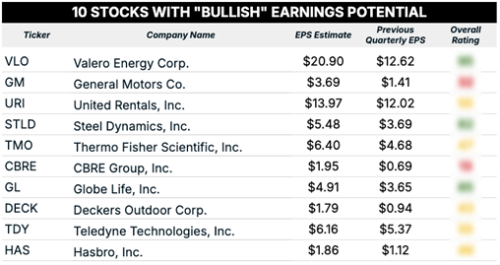
Valero Energy Corp. (VLO) reports third-quarter results before the opening bell on Thursday, October 22.
And the expectations are huge.
Analysts are looking for earnings of $20.90 per share – up 66% from last quarter’s $12.62 mark.
Is that realistic?
Let’s look at what Valero just did.
In the second quarter, Valero’s refining segment generated $4.5 billion in operating income. A year earlier, that number was $1.3 billion.
The company also handed $2.6 billion back to shareholders through dividends and buybacks in that quarter alone.
Now, here’s the thing about refiners: They don’t make money on the price of oil.
They make money on the spread — the gap between what they pay for crude and what they get for gasoline and diesel.
Wall Street calls it the “crack spread.”
Right now, that spread is fat.
Distillate inventories are low, and crack spreads are elevated.
That’s the sweet spot for a big independent refiner like Valero, which runs 14 refineries with about 3 million barrels per day of capacity.
Wall Street has taken notice.
Several firms raised their price targets on Valero in early October. When analysts chase a stock higher into earnings, it suggests the profit picture is improving faster than their models imply.
Is there risk?
Of course.
Remember that 2027 cliff.
Refining margins can compress fast, and Valero won’t be immune when the YOY comparisons get tough.
But for this quarter, Valero is in the right place at the right time.
That’s why it tops my bullish list heading into next week.
“Bearish” Earnings to Watch
For our “bearish” earnings screen, we’re only looking for two things:
- 10 or more analysts must cover the stock.
- The average analyst estimate for the current quarter’s EPS is less than the previous quarter’s.
We want companies that are covered by a sufficiently large group of Wall Street analysts who collectively expect the company to report a quarter-over-quarter (QOQ) decline in earnings.
Here are 10 companies that passed this screen:
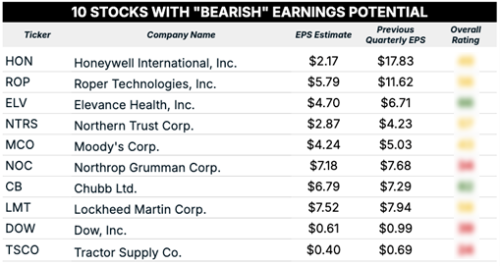
Now for the other side of the ledger.
Tractor Supply Co. (TSCO) is set to report third-quarter earnings before the market opens on Thursday, October 22.
Analysts expect earnings of $0.40 per share. That’s down from $0.69 last quarter. And compared with the same quarter a year ago — when Tractor Supply earned $0.49 — it’s an 18% drop.
Some of that sequential slide is seasonal.
Spring and early summer are Tractor Supply’s busy season. Fall is quieter.
But the bigger problem is the trend.
Tractor Supply has missed Wall Street’s earnings estimates three quarters in a row — in fourth-quarter 2025 and the first two quarters of 2026.
Then in July, management cut its full-year outlook. It now expects earnings of $1.90 to $2.00 per share. Back in January, it was guiding for between $2.13 and $2.23. Revenue guidance came down, too.
Here’s where it ties back to energy.
Tractor Supply’s customers are rural. They drive long distances, they run equipment and they feel every penny of higher fuel prices.
In my view, $85 oil is a windfall for Valero… and a tax on Tractor Supply’s core shopper.
When a company misses three straight quarters and cuts guidance, I don’t want to be the one betting on a turnaround the week of earnings.
Tractor Supply tops my bearish list.
The Bottom Line
Energy is the earnings story of 2026. But the data says the clock is ticking.
Lean into the winners while the window is open. And watch out for the companies paying the price for $85 oil.
Check out both tables above for the full list of stocks with bullish and bearish earnings setups heading into next week.
Until next time…
Safe trading,
Matt Clark, CMSA®
Chief Research Analyst, What My System Says Today